Why the pure DTC playbook lost its edge, and why franchising remains a powerful engine of global brand growth
For much of the past decade, the formula seemed almost irresistible: cut out the middleman, sell directly to consumers, own the customer data and keep more of the margin. Venture capital flowed into digitally native brands built around websites, social media and performance marketing, while physical retail was often treated as an expensive legacy model.
By 2026, the story has become considerably more complicated. The direct-to-consumer model did not disappear. It matured. And as customer-acquisition costs, fulfilment expenses, returns, inventory requirements and the cost of building physical reach became harder to ignore, many brands began moving beyond the idea that being “DTC” was itself a growth strategy.
Allbirds offers a revealing example. Once one of the defining names of digitally native retail, the company closed its remaining full-price U.S. stores in February 2026 and said it would focus resources on e-commerce, wholesale partnerships and international distribution. Its 2025 revenue fell to $152.5 million from $189.8 million the previous year, while it reported a $77.3 million net loss.
That does not mean DTC is dead. It means pure-play DTC is no longer the only growth equation.
At the same time, franchising continues to demonstrate the power of distributed ownership. In the United States, the International Franchise Association projects approximately 845,000 franchise establishments, nearly 8.9 million jobs and more than $920 billion in economic output in 2026.
The contrast is revealing. DTC asks a brand to retain control and carry much of the cost of reaching the customer. Franchising asks the brand to build a system that other entrepreneurs can invest in, operate and scale locally.
One model concentrates ownership. The other distributes it.
And when brands move across cities, countries and continents, that difference becomes more than a question of distribution. It becomes a question of capital, risk, speed, control, local knowledge and who is responsible for making the business work on the ground.
The real debate in 2026, therefore, is not whether DTC or franchising is the universal winner. It is where each model creates the most value, and why an increasing number of brands are combining elements of both.
The Two Competing Bets on Growth
Direct-to-consumer is a bet on ownership. The brand controls pricing, branding, customer data, and the full journey from discovery to delivery. In theory, it captures the entire retail margin. In practice, it also absorbs every cost: customer acquisition, fulfillment, returns, inventory risk, and the capital required for any meaningful physical presence.
Franchising is a bet on leverage and local entrepreneurship. The franchisor provides the brand, operating system, training, and ongoing support. Independent franchisees invest their own capital, own the local business, and carry primary responsibility for day-to-day execution, staffing, and often inventory. The franchisor earns initial fees and ongoing royalties; the franchisee keeps the residual profit and bears the residual risk.
These are not minor differences in distribution. They are competing philosophies of growth.
The Economics That Changed the Conversation
Pure DTC looked brilliant when digital advertising was relatively cheap and capital was abundant. Once privacy changes, rising acquisition costs, and higher interest rates arrived, the economics shifted. Many digital-native brands found that the “higher margin” advantage was eroded by heavy marketing spend, complex logistics, and high return rates. Building physical stores, once dismissed as outdated, proved expensive and operationally demanding when done entirely with company capital.
Franchising faces its own realities: royalties, marketing contributions, compliance requirements, and the ongoing need to support a network of independent operators. Yet its capital structure is fundamentally different. A franchisor can expand into new markets without funding every real estate commitment, build-out, and working-capital requirement. Franchisees, with personal capital at stake, often bring a level of local intensity that centralized teams struggle to match.
The automotive sector offers one of the clearest data points. A detailed 2024 Oliver Wyman study, commissioned by the National Automobile Dealers Association, examined the true net cost of distribution. Contrary to claims that traditional dealer franchises added unnecessary expense, the research found that at mass-market scale the franchised model delivered a lower net cost of distribution than pure direct-to-consumer or hybrid approaches, by roughly $110–170 per vehicle once inventory holding, local price optimization, and customer-level deal customization were properly valued.
Real-World Lessons: Dunkin’, Starbucks & the DTC Survivors
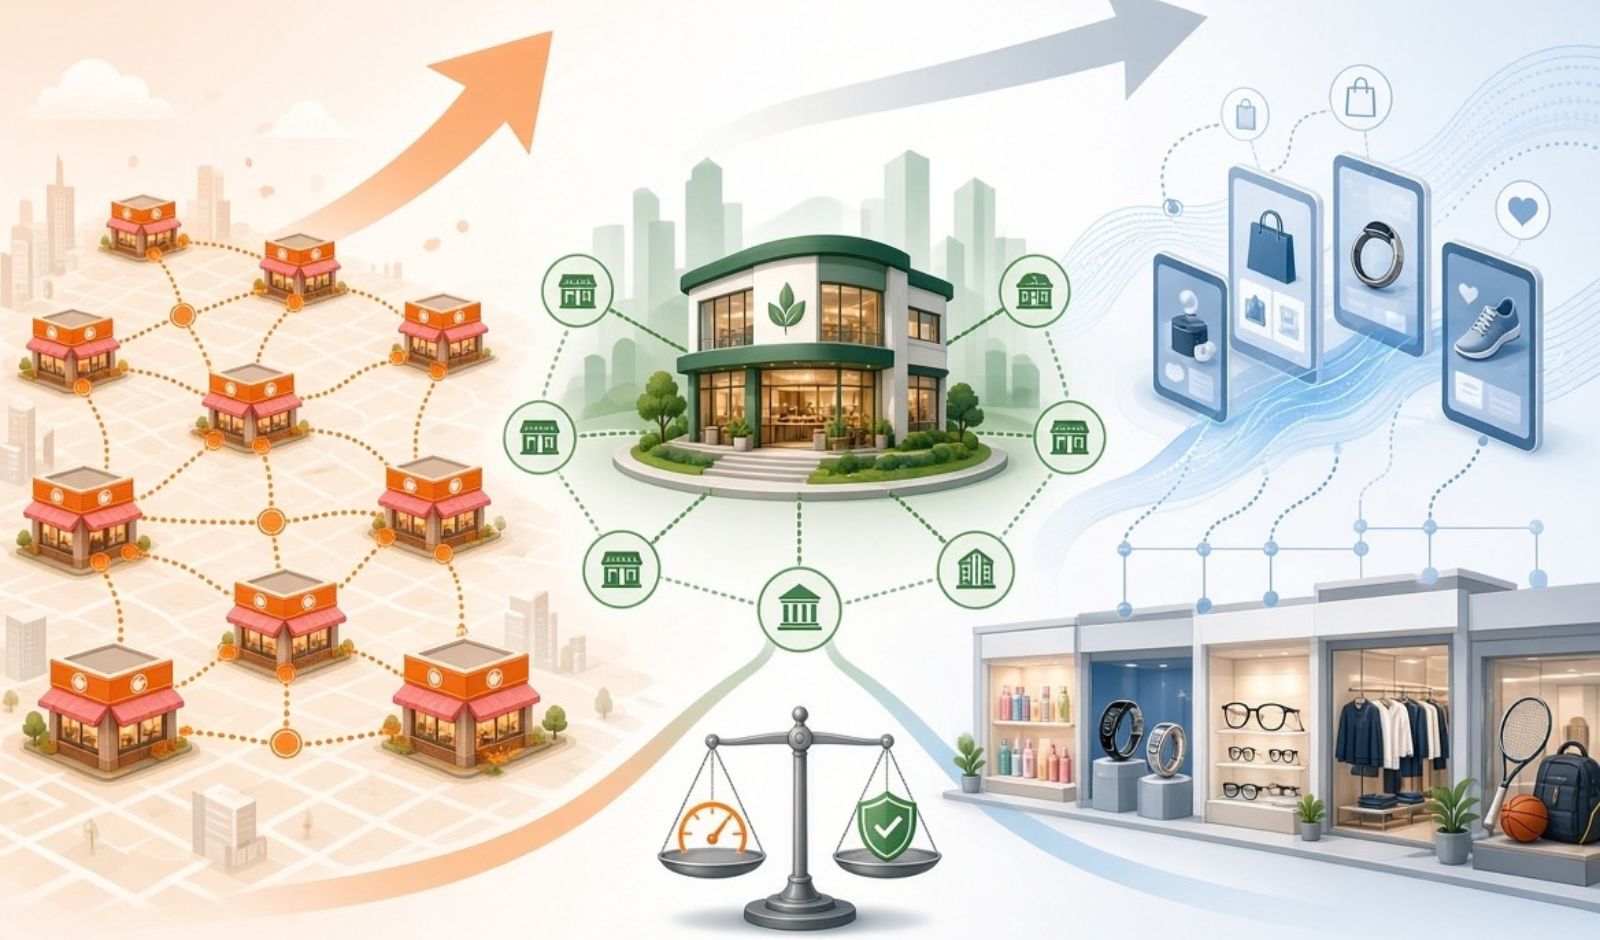
The contrast between Dunkin’ and Starbucks remains instructive. Dunkin’ has long operated as a heavily franchised system, enabling rapid, capital-light expansion. Starbucks has historically maintained a higher proportion of company-operated stores to protect experience and brand control. Both built powerful global businesses, but they made different trade-offs between speed, risk, and consistency.
On the DTC side, the brands that endured did not stay pure. Glossier expanded into Sephora and generated substantial wholesale revenue. Oura moved beyond direct channels into Best Buy and Target. Warby Parker and Vuori built productive physical retail alongside digital. Even digitally native success stories discovered that stores can serve as powerful brand platforms, lower return rates, and acquire customers more efficiently than paid media alone.
Meanwhile, established retailers and multi-brand operators are increasingly adopting hybrid approaches. Decathlon, for example, has long used franchising in certain international markets and is now expanding the model in Italy, aiming for dozens of additional franchise locations by 2030 while continuing to operate company stores. The logic is clear: local partners can better adapt to regional differences while the brand maintains standards and product focus.
Global Expansion Changes the Equation
For brands thinking internationally, the choice becomes even sharper. Entering new countries through pure company-owned DTC requires significant capital for local entities, inventory positioning, regulatory compliance, marketing localization, and physical presence. Franchising, particularly through master franchise or area development agreements, allows brands to partner with operators who already understand the market, share the investment burden, and accelerate density.
This is why so many global systems rely on franchising for cross-border growth. Local partners bring relationships, cultural fluency, and operational knowledge that a distant headquarters cannot easily replicate. At the same time, sophisticated franchisors layer digital capabilities, shared data platforms, and strong brandstandards on top of the traditional franchise relationship.
The Hybrid Reality of 2026 and Beyond
The most successful brands today rarely treat channel strategy as an identity. They treat it as a toolkit. Direct digital channels excel at data capture, storytelling, and high-intent sales. Company-owned stores can serve as flagships and innovation labs. Franchised units deliver density, local relevance, and capital-efficient scale. Selective wholesale or distribution partnerships can open doors in markets where full ownership or franchising is not yet optimal.
The pure “DTC brand” identity has largely faded because it proved too rigid. The pure “we only franchise” approach can also limit control in certain strategic markets. The winners combine both with intention.
What This Means for Franchise Stakeholders Worldwide
For emerging franchisors, the DTC era delivered a valuable stress test: unit economics still matter more than channel fashion. Brands that cannot make a single location work profitably will struggle regardless of how they distribute.
For franchisees and multi-unit operators, the comparison reinforces the enduring value of ownership. Local operators who execute well, manage costs tightly, and understand their communities continue to build resilient businesses even when digital acquisition costs rise or consumer preferences shift.
For global brand builders and investors, franchising remains one of the most proven mechanisms for achieving geographic coverage without exhausting the balance sheet, especially across diverse regulatory and cultural environments.
The last decade did not crown a permanent winner between direct-to-consumer and franchising. It clarified the strengths and limits of each. Direct-to-consumer is a powerful channel. Franchising is a powerful system for scalable, locally rooted growth. The brands that will thrive in the years ahead are those that understand the difference, and deploy both with clear-eyed strategy rather than ideology.